

Picture the shopping decision a year or two from now…
A person doesn’t open a website, scroll through options, or weigh a familiar brand against an unknown one anymore. They ask. An agent scans the market and returns a single recommendation - or simply places the order.
The deliberation that once happened inside a human head, shaped by habit, loyalty, advertising, and friction, now happens inside a machine that feels none of it. The store quietly disappears from view.
That is the image behind the emerging consensus on AI and retail. And the consensus reads it as a threat…
If a machine compares every option in milliseconds, price discovery collapses and margins compress. If discovery moves to a surface the retailer doesn’t own, the retailer becomes an interchangeable supplier. For much of the industry, that fear is justified. Grocery, CPG, apparel, and footwear all look exposed.
But, for Amazon, the logic runs in reverse.
An agent doesn’t buy on instinct or affection. Instead, it optimizes against measurable variables: price, delivery speed, availability, reliability, satisfaction, return friction, and the value of a loyalty membership.
Those are exactly the dimensions Amazon has spent 20 years and hundreds of billions of dollars engineering itself to win.
That is the core argument of this piece: the agentic shopper, stripped of sentiment, becomes a perfectly rational evaluator of the moat Amazon already owns.
The Agentic Commerce Era:
Despite the frenzy, it’s important to start the discussion by saying that this technology is still very new - and that AI platforms still account for less than 1% of web traffic across major e-commerce sites.
The future people imagine, where your agent quietly reorders detergent or books the cheapest equivalent flight, is still distant. For now, it mainly serves to show you what to buy, not where to buy it.
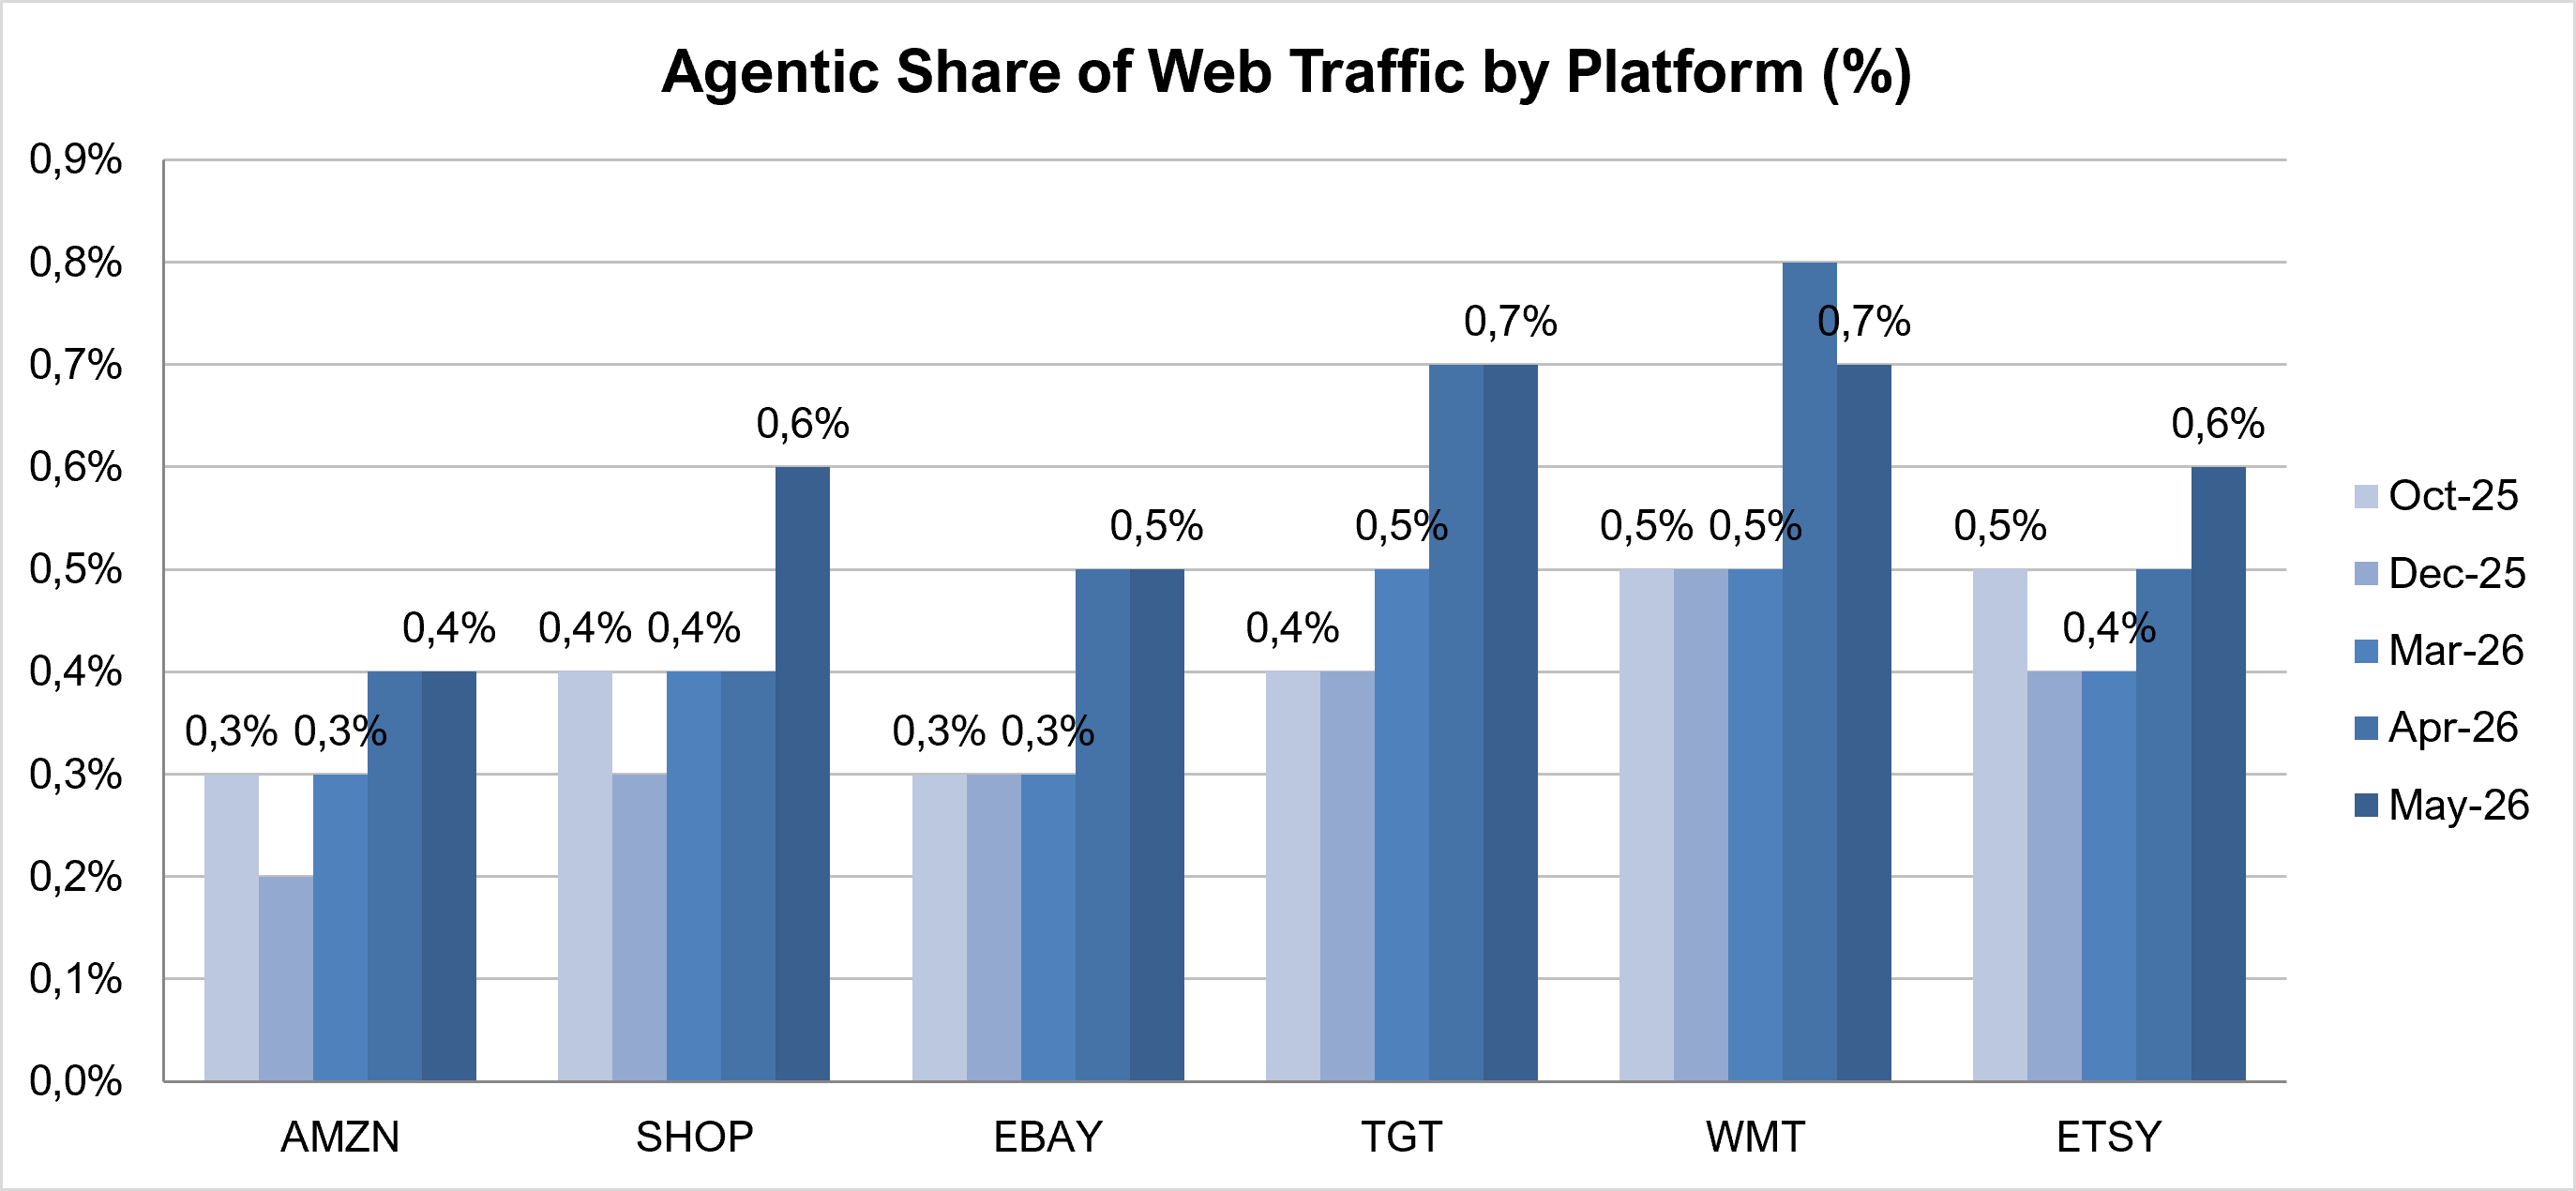
Despite being small, the traffic is very qualified. Shoppers who arrive through an AI recommendation convert far better than those who come through almost any other channel, in some measurements around +50% higher and spending more per order, with AI-referred traffic converting ~42% better than non-AI traffic in one recent period.
The reason is relatively intuitive, since someone who asks an agent what to buy has already decided to buy something. What is left is getting it to them.
Agentic commerce has three layers: (i) discovery, (ii) conversion, and (iii) infrastructure.
Discovery is where the shopping journey begins.
Conversion is where the retailer turns intent into a customer relationship.
Infrastructure is everything beneath both layers: the payments, logistics, warehouses, delivery networks, and physical capacity required to complete the order.
The market’s fear lives almost entirely in the 1st layer. The concern is that whoever owns discovery will eventually own the economics.
But an agent can recommend almost anything and still cannot ship a single box. The companies that built the warehouses, trucks, fulfillment systems, and distribution networks still control the hard part of commerce. And most brands have little interest in handling that burden themselves.
Found this content valuable? Share it with your network! Help others discover these insights by sharing the newsletter. Your support makes all the difference!
The Logistics Moat:
When I first wrote about Amazon’s logistics moat a year and a half ago, back when Jimmy’s Journal had only 200 subscribers (link here), I did not imagine it would be so strongly reinforced by AI agents.
Today, the company is the largest parcel network in the United States by volume. It moved an estimated 6.9B parcels in 2025, 31% of the market, ahead of both USPS and UPS.
By revenue, it ranks 3rd, at around $33B and a ~16% share, which means it has won the high-volume, low-cost end of shipping rather than the premium end.
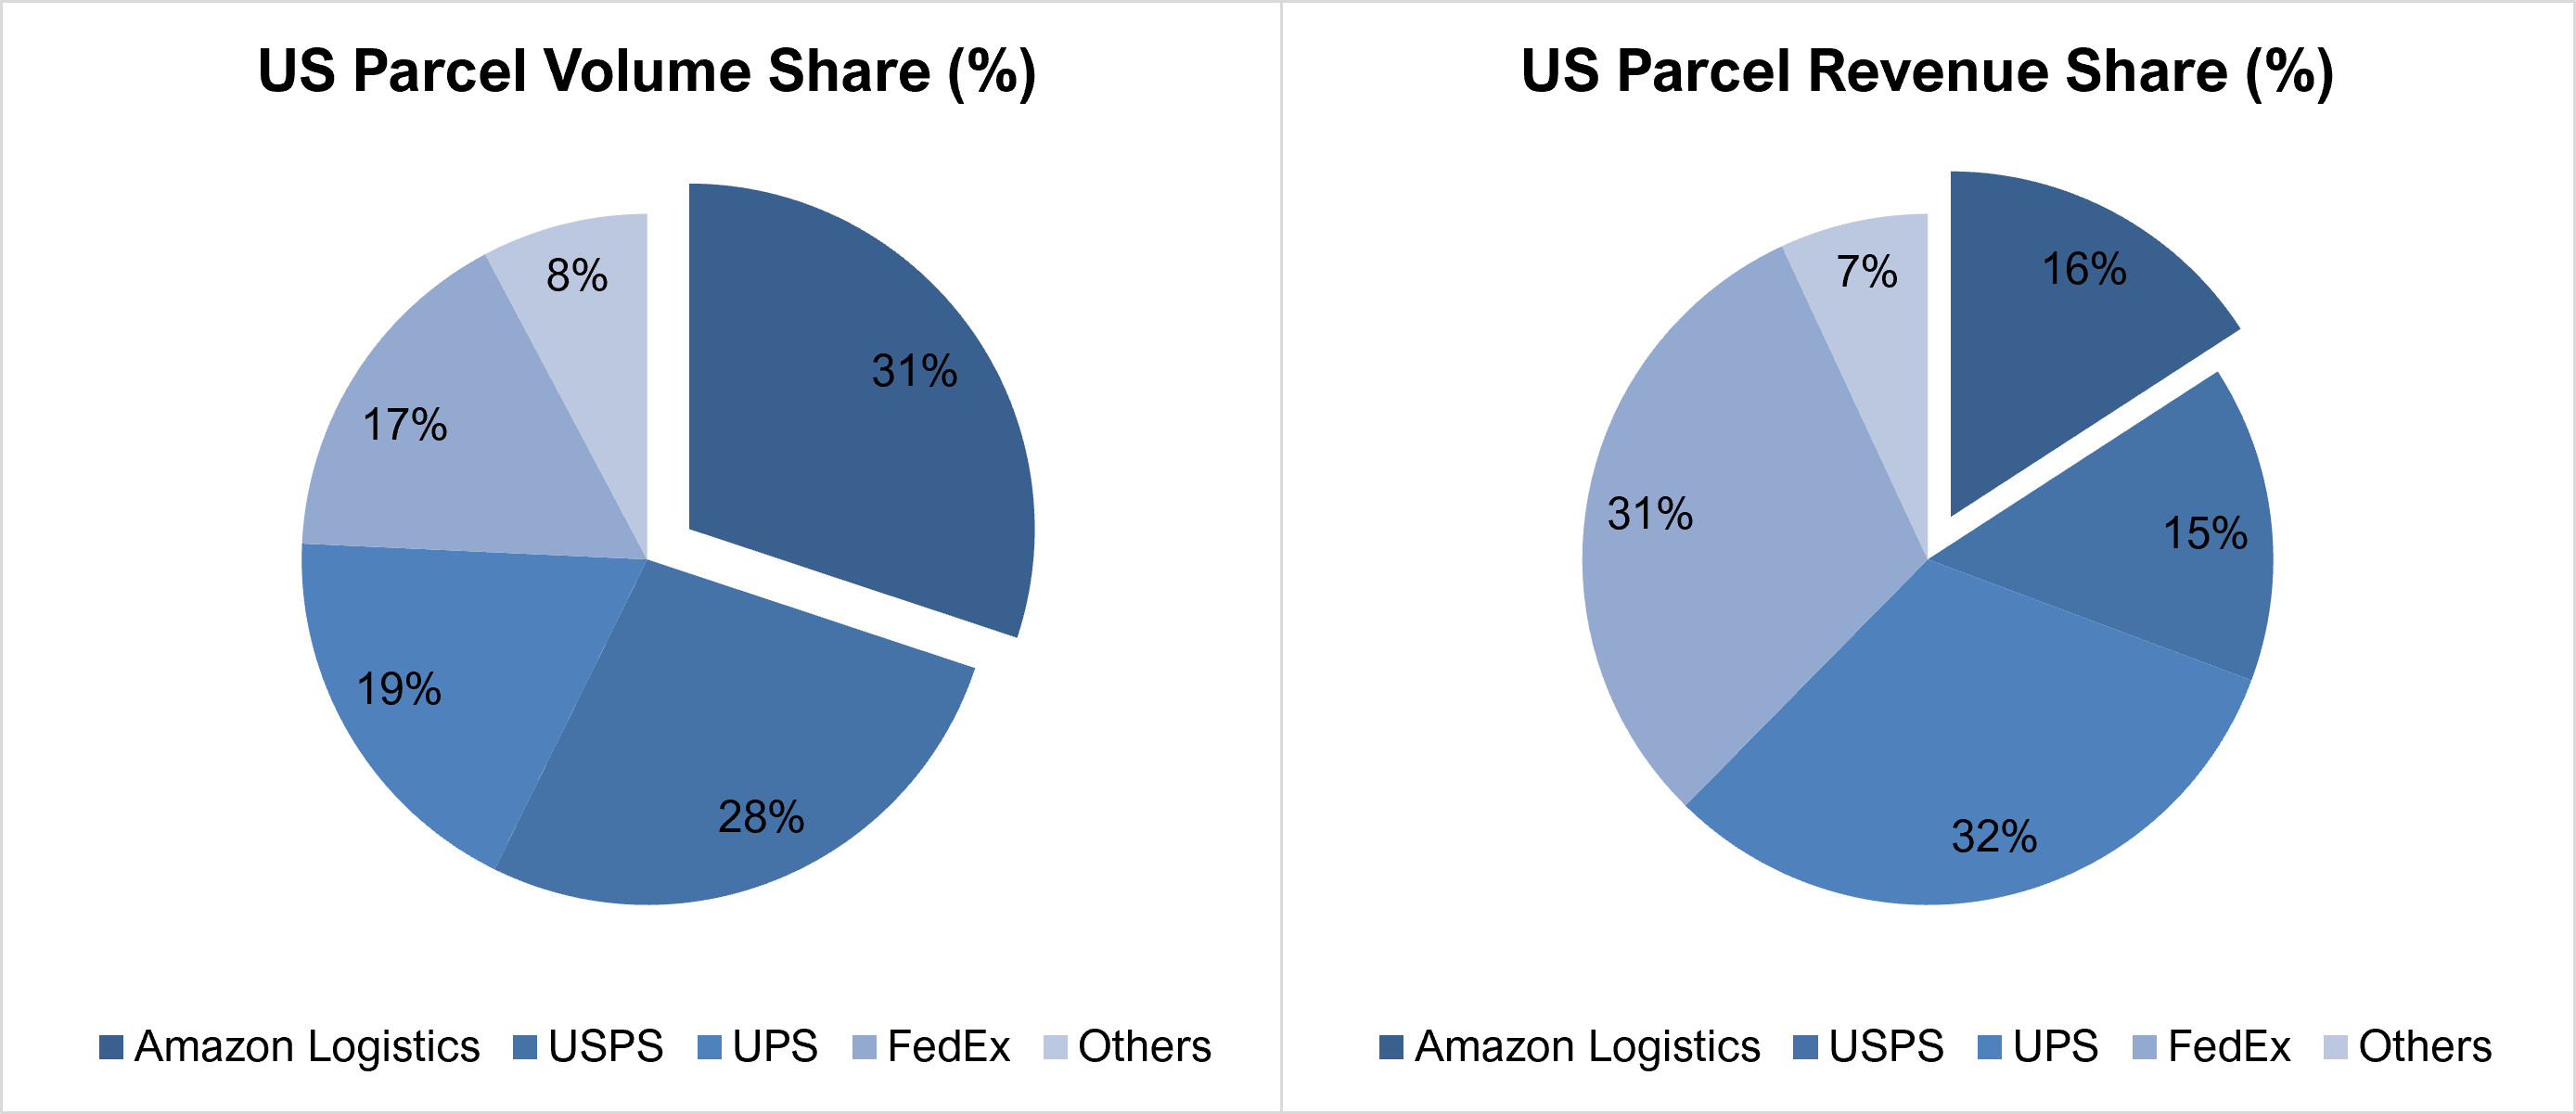
Nearly 2/3 of Amazon’s own packages now travel through its own network, and a planned reduction in USPS volume should push that even higher.
The best part is that, as the network becomes denser, delivery speed improves - and the cost of providing it falls.
Reorganizing the US network into regional hubs has steadily lowered the cost to serve (CTS), and it showed up in the Q1, when unit volume grew +15% y/y, the fastest pace in 3.5 years.
Amazon delivered more than 13B same-day or next-day items globally in 2025, runs more than 85 same-day sites stocking its top 90,000 products, and has pushed that speed out to more than 4,000 smaller cities, towns, and rural areas.
It is spending $4B to triple the rural network.
More than a 1M robots and a growing layer of software now handle forecasting, inventory placement, pick paths, and routing.
No competitor can buy its way into this. The money can be raised and the engineers can be hired, but the density, national coverage, and years of operating experience behind it cannot be compressed into a roadmap.
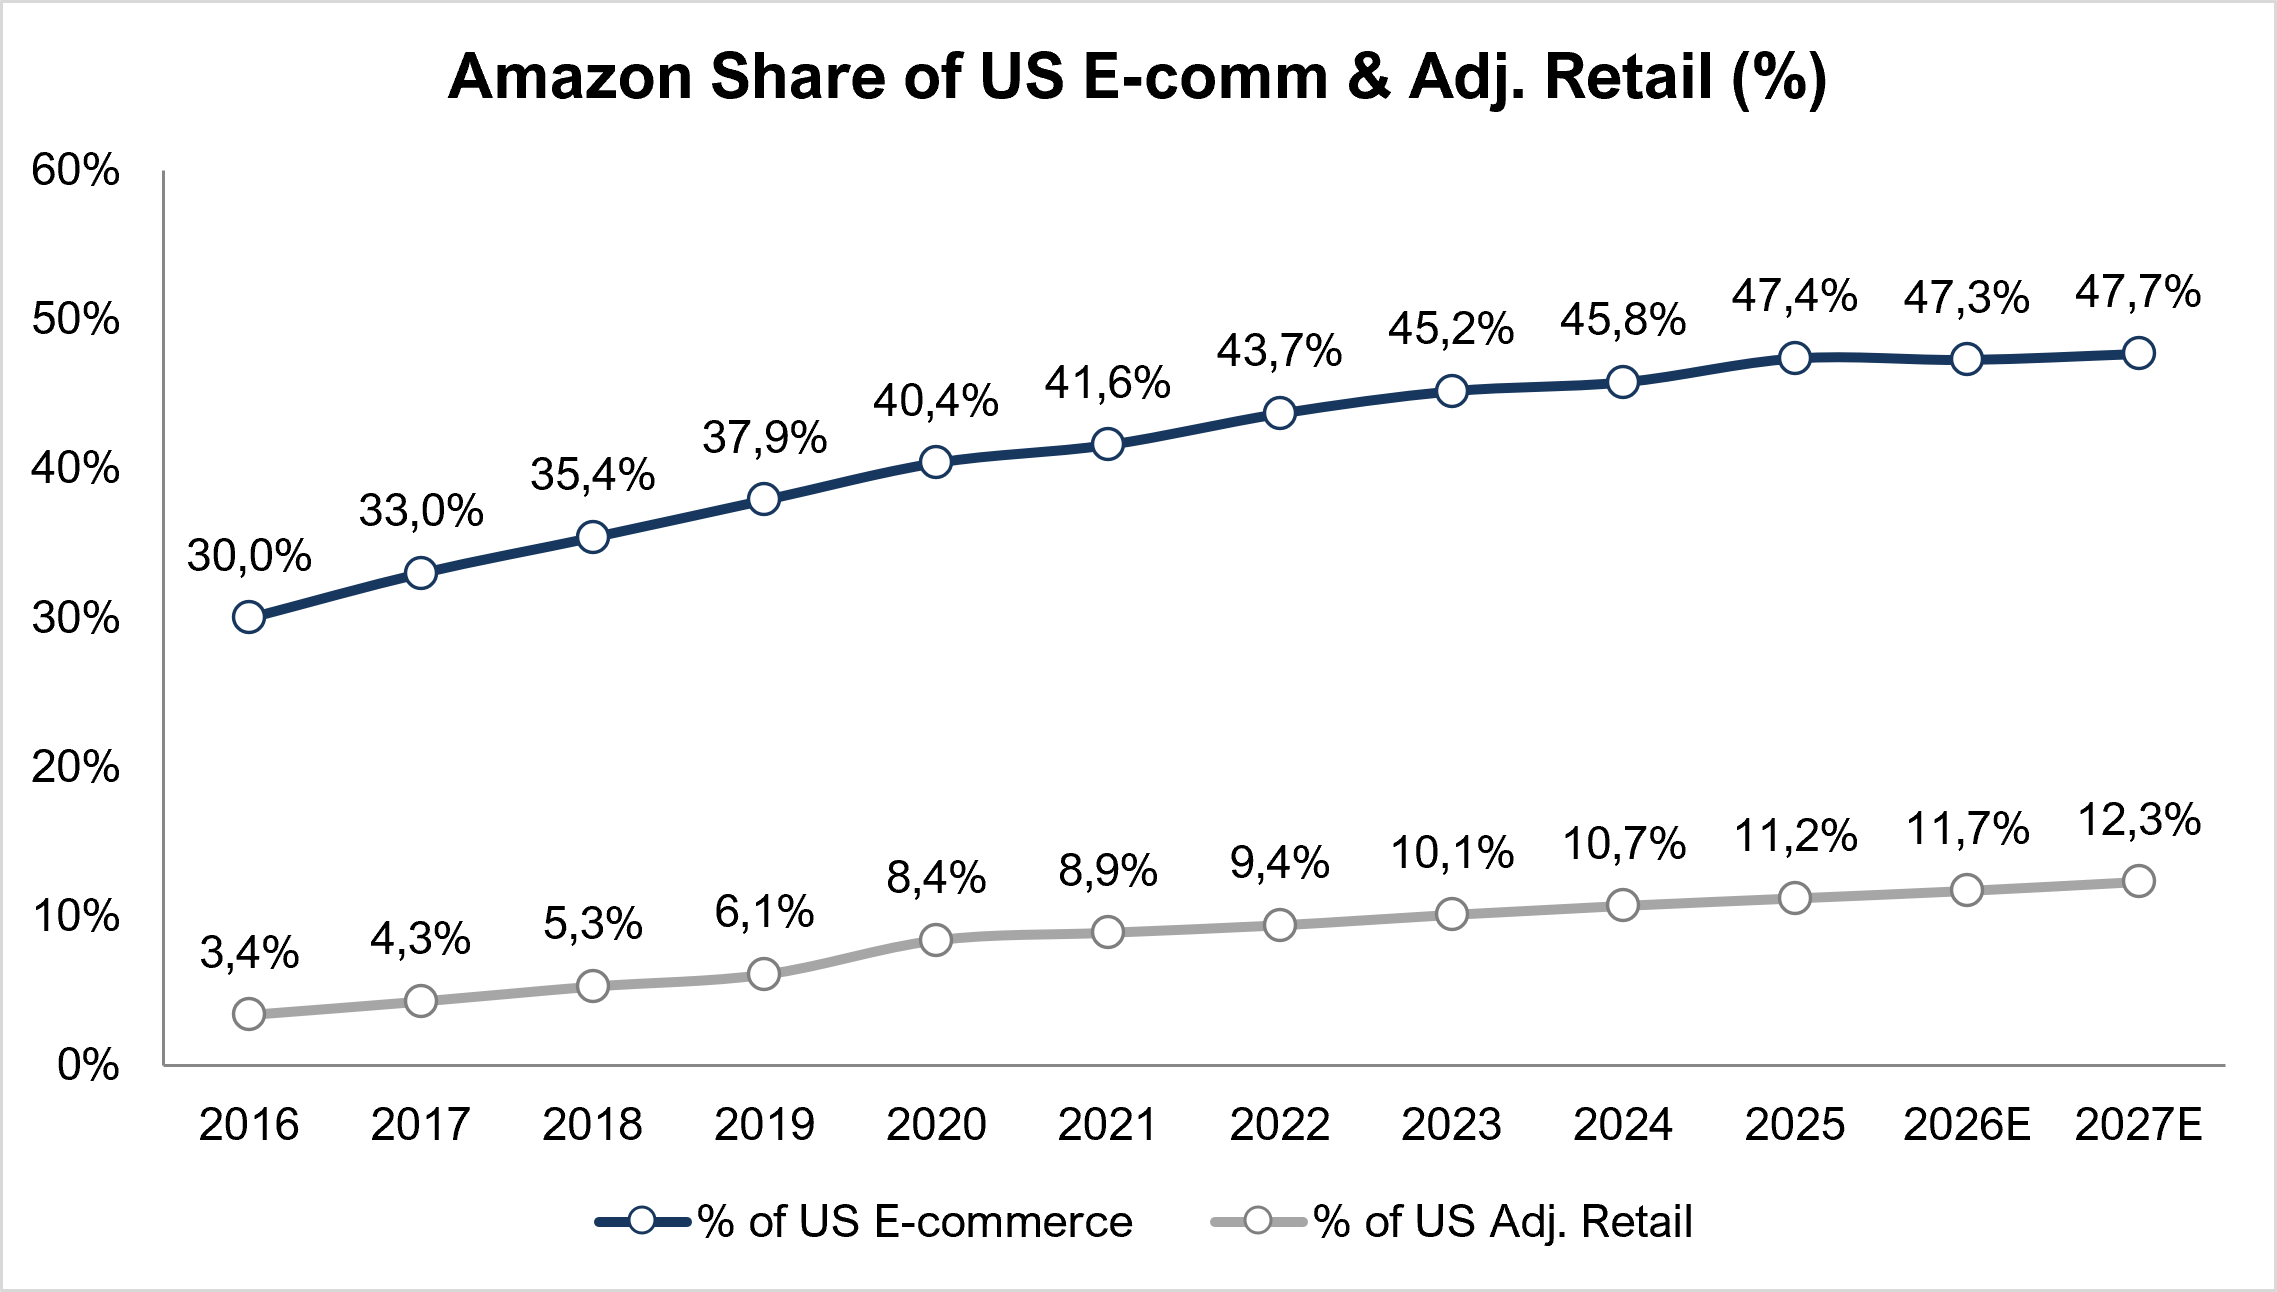
And now, what was once considered a “cost center” has become a source of revenue. Through Amazon Supply Chain Services, Amazon now sells freight, distribution, fulfillment, and parcel shipping to other companies, turning spare capacity into revenue.
According to market estimates, around ~70% of 3P transactions already run through Amazon’s fulfillment network, and the company earns a blended take rate near 30% on those sales, with room above it.
The same network that protects the core business has become a product in its own right.
Why the Moat Grows Stronger?
When humans did the shopping, Amazon’s delivery edge mostly worked as defense.
Faster shipping and a lower cost to serve protected share and margin, but plenty of purchases still ran on habit, on brand attachment, on which store was nearby, or on inertia about where someone already had an account.
A better supply chain helped without often being the thing that closed the sale, because the buyer was not scoring every option against it.
An agent does precisely that.
When it answers a request, it weighs the options on what it can measure, and delivery speed, price, availability, and the value of a membership are exactly the comparable signals it ranks on.
Amazon’s network stops being a quiet cost advantage and becomes a reason to get recommended at all. Whichever company can promise the item today, at a fair price, with the best odds of it being in stock, is the one the agent puts forward.
Amazon no longer has to win the shopper over. It has to clear the bar the machine already measures, and it built the entire business to clear that bar.
So the shift the market reads as a threat does close to the opposite for Amazon. It takes the part of the advantage that used to be invisible, the reliability under the order, and makes it the first thing the new buyer sees.
Enjoying the content? Subscribe to Jimmy’s Journal Pro and unlock deeper insights, institutional-grade analysis, and practical frameworks you can actually apply.
Rufus or… Alexa for Shopping?
Andy Jassy, Amazon’s CEO, is certainly not waiting for someone else’s agent to send him customers - he has already started building his own.
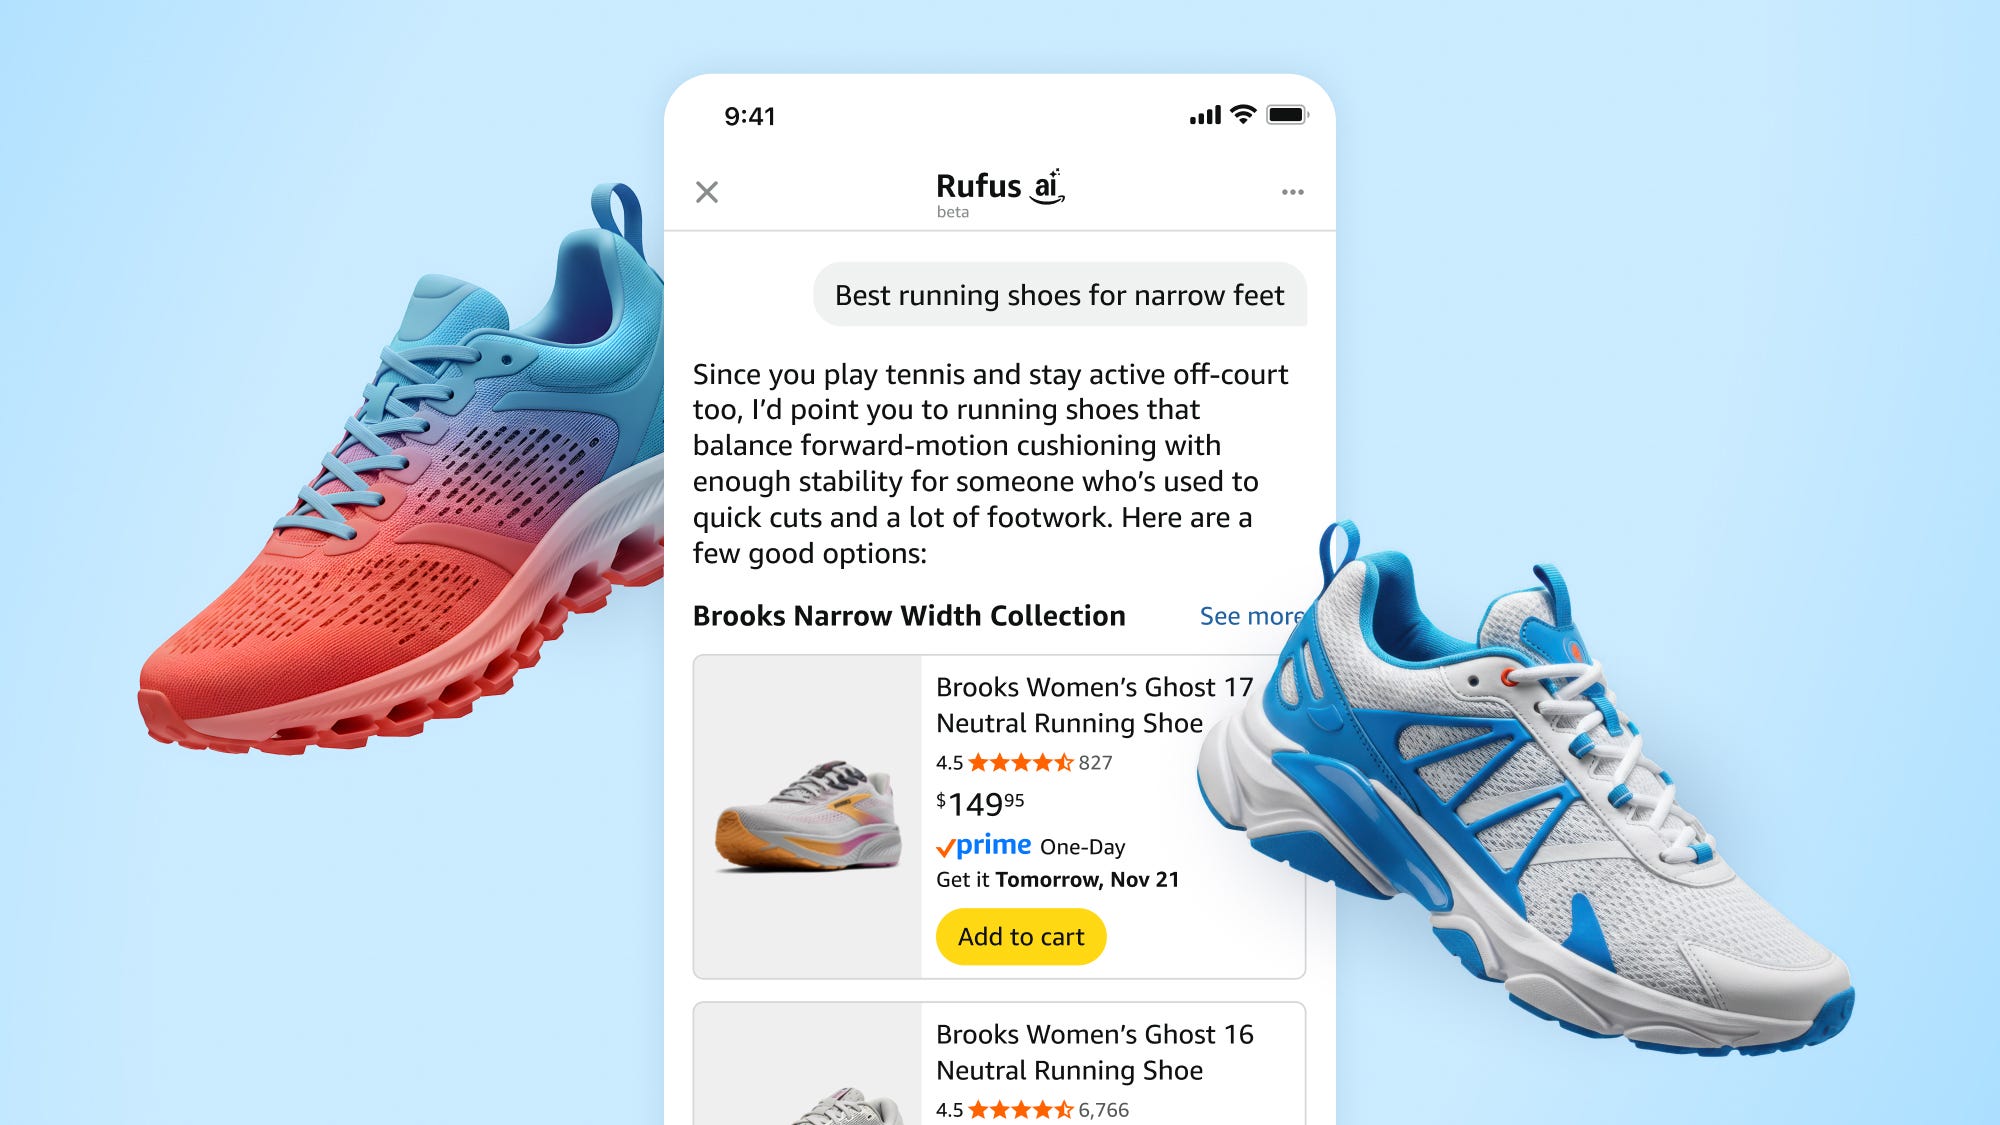
Rufus, Amazon’s AI shopping assistant inside its apps, now rebranded as Alexa for Shopping, is scaling very fast.
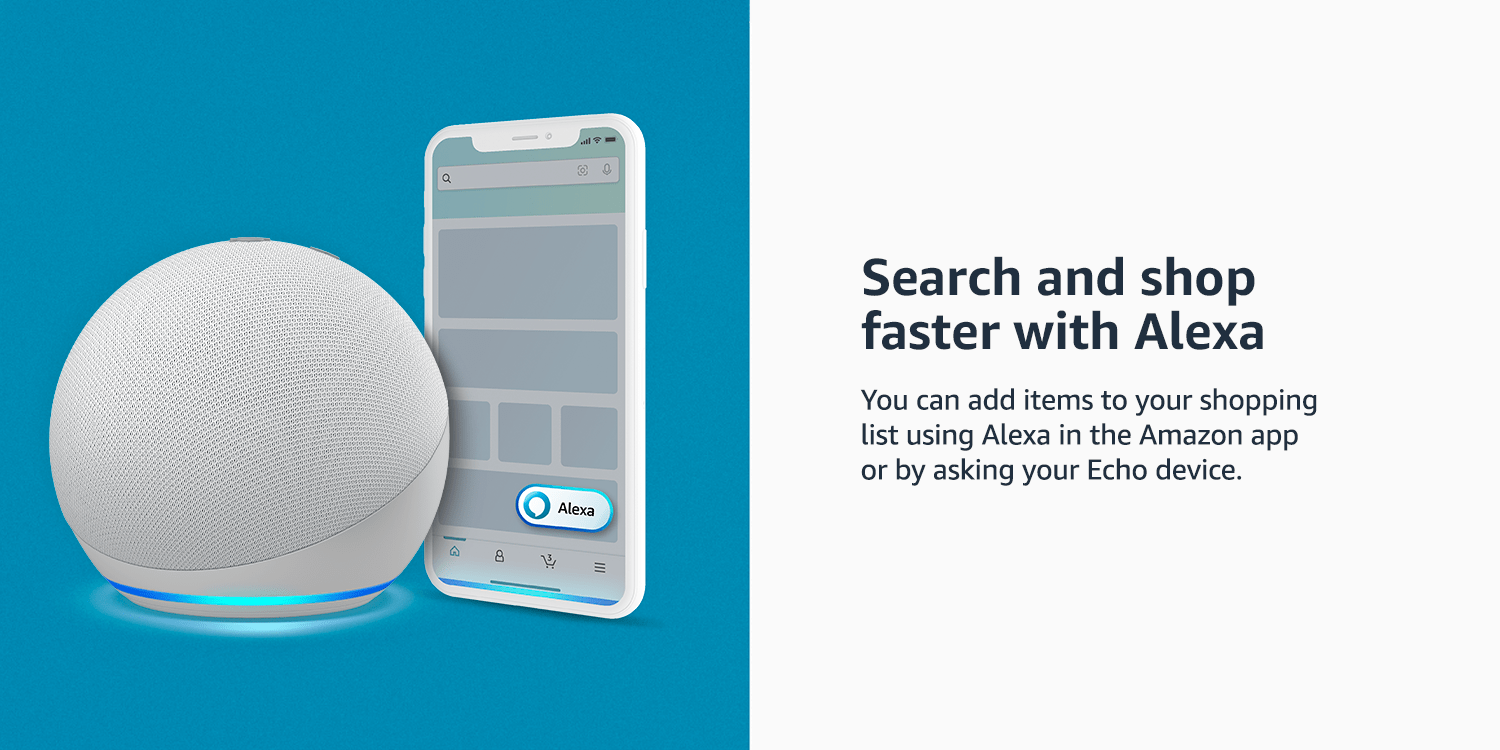
Monthly users (MAUs) were up more than +115% and engagement more than 400% y/y in Q1, while shoppers who use it are about 60% more likely to buy. Management credits it with around $12B in incremental annualized net sales in 2025.
The feature list reads like the job description of a competent buyer working for you:
tracking prices,
building guides,
purchasing when an item hits a target price,
reordering, and
managing the cart.
Most other retailers are taking the opposite route. They are wiring their catalogs and checkout into OpenAI, Google’s Gemini and AI Mode, or Microsoft Copilot, much of it still in pilot mode.
Amazon keeps it in house.
It runs its own assistant and skips most of the external checkout integrations because it owns the place where demand starts: the data, the catalog, and the delivery network underneath it.
A retailer whose agentic plan is mostly a list of other companies’ platforms is renting access to its own customers.
Not the case for Amazon.
The Competitive Battlefield:
Amazon doesn’t have the field to itself, and there is one competitor that truly keeps the company awake at night: Walmart ($WMT).
The largest physical retailer in the world is building its own version of the same machine, called Sparky. Meanwhile, its marketplace reached an estimated $19B in GMV and grew about +35% in 2025, accelerating toward +50% in Q1 2026. Walmart+ is growing double digits to almost 22M members.
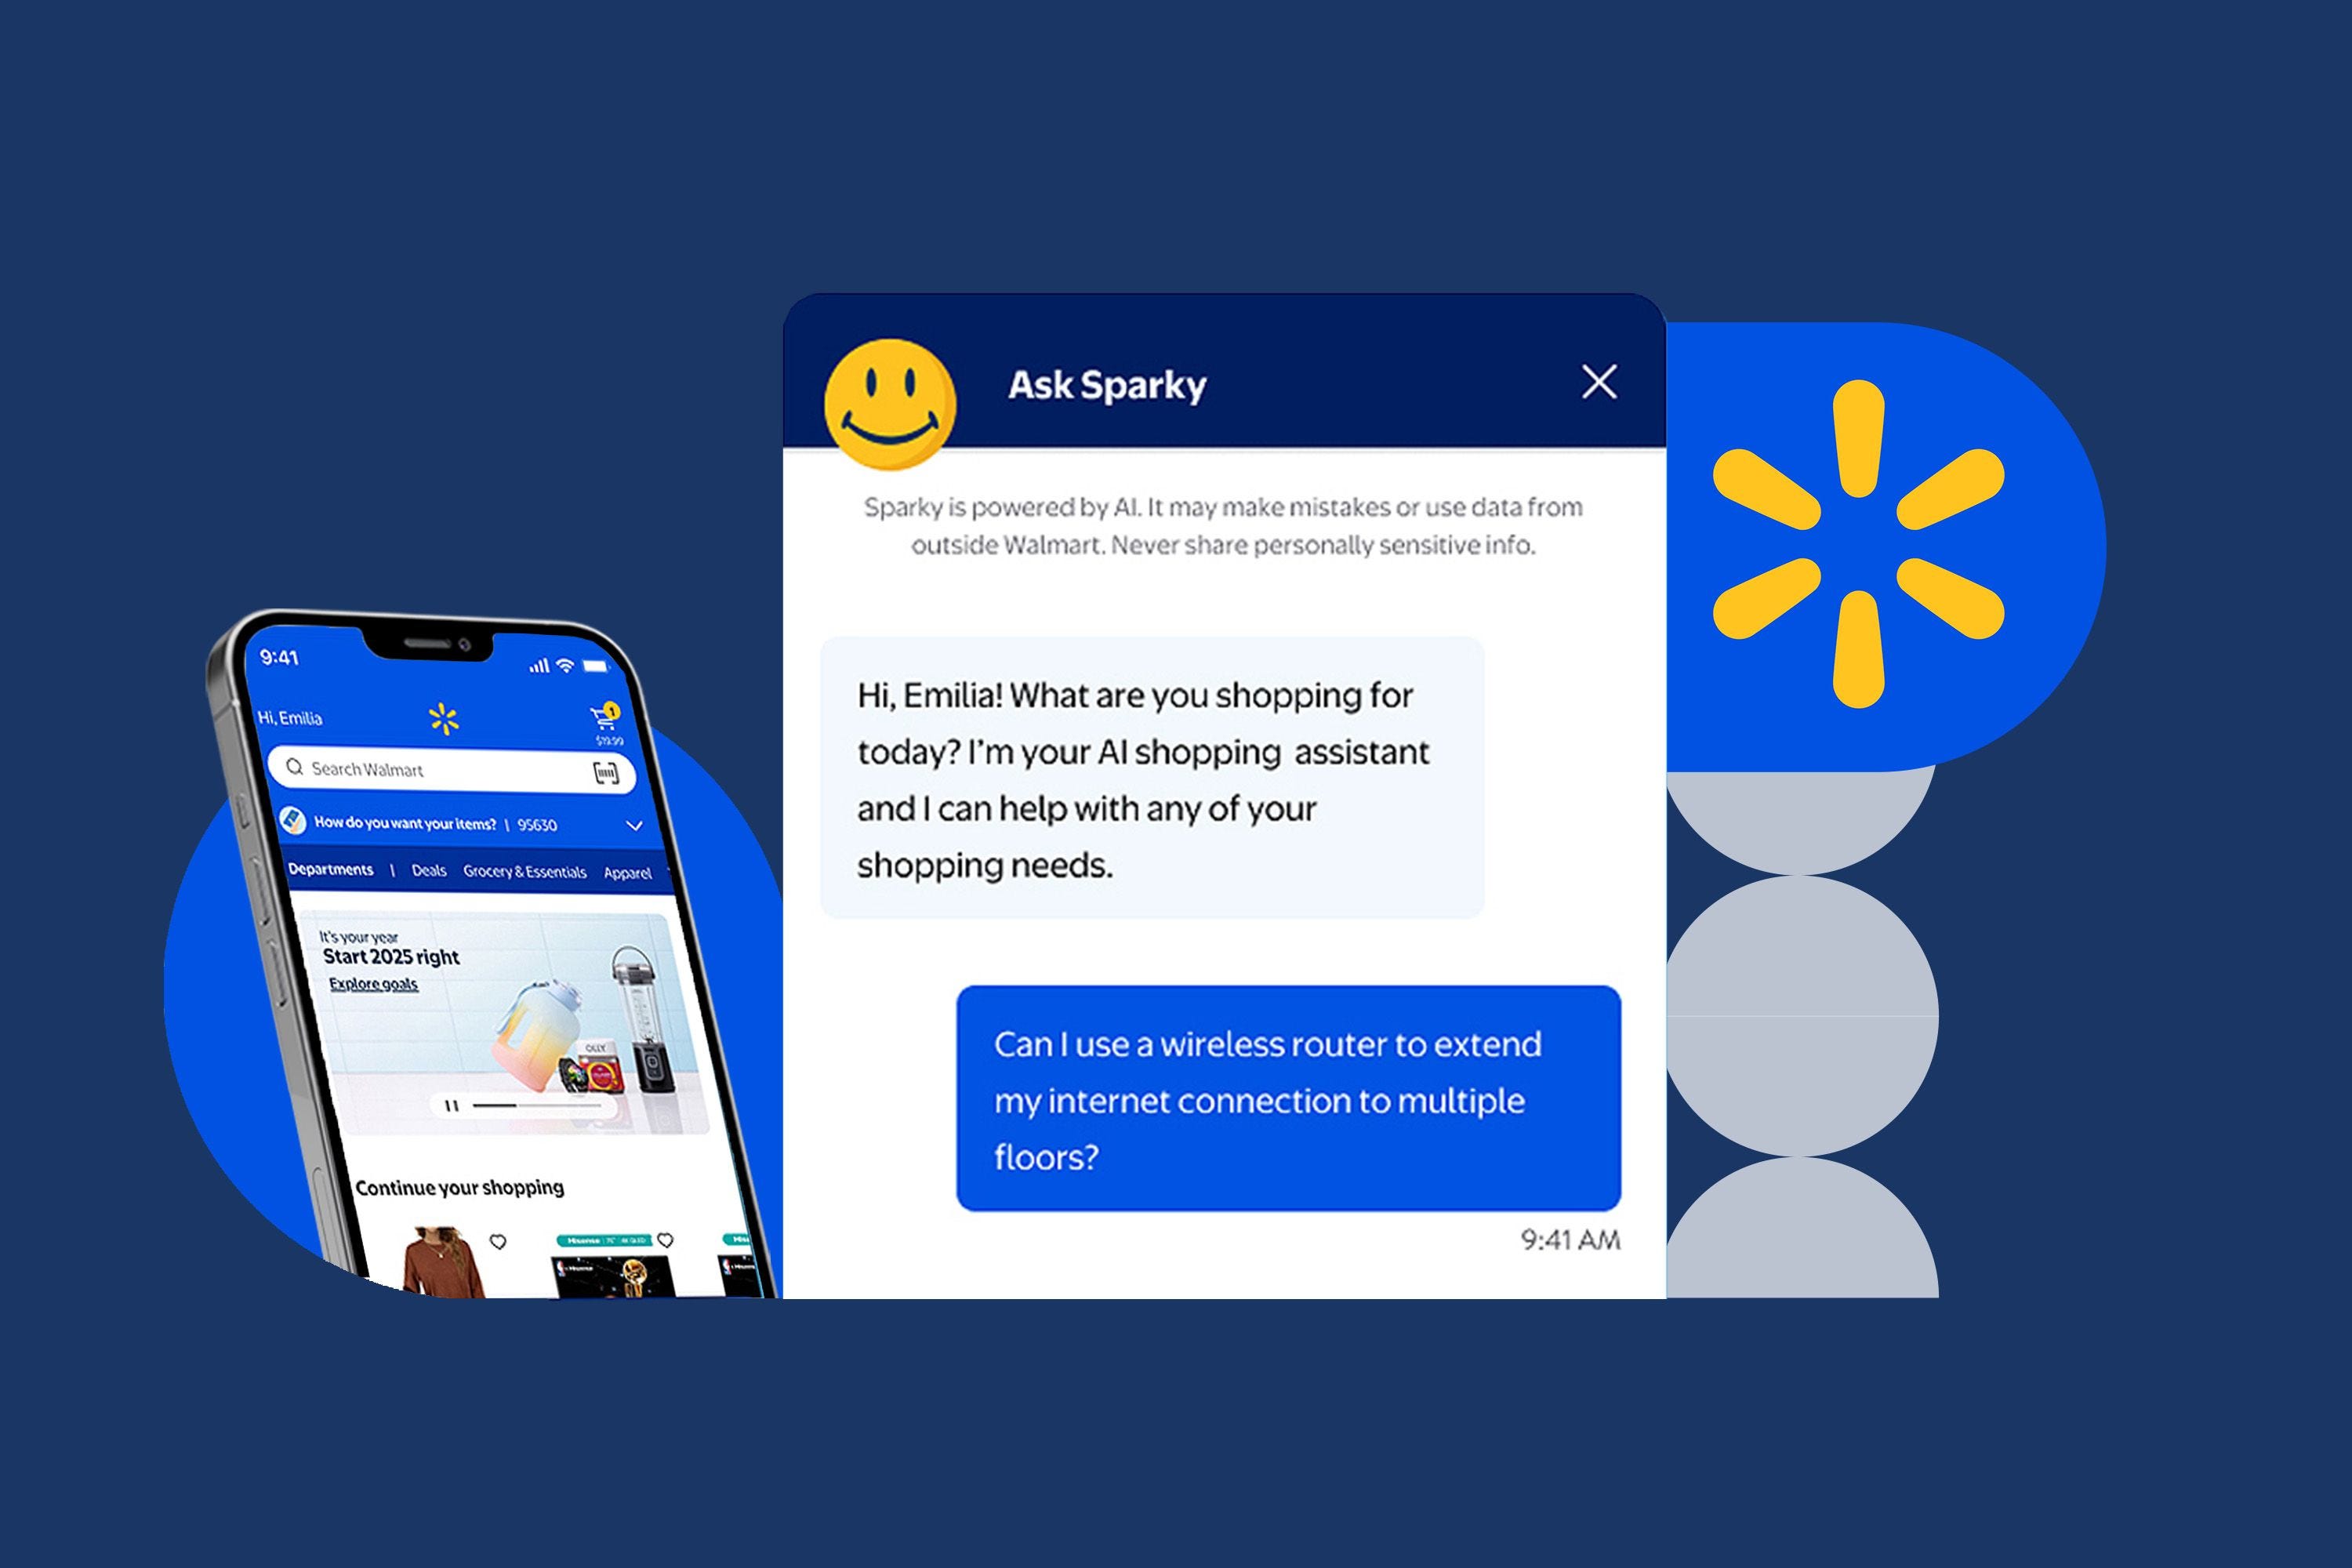
Advertising and membership, the high-margin pieces of the business, already drive about 1/3 of Walmart’s US operating profit on less than 2% of revenue.
Walmart leads outright in two areas:
grocery, where it dominates US share, and
agentic partnerships, having moved early with Google.
In same-day grocery, it reaches nearly 95% of US households.
Both companies are trying to invade each other’s backyard, but scale still keeps the balance tilted toward Amazon.
Prime households outnumber Walmart+ households by something like 4.3x. In general merchandise, where the richest agentic monetization sits, Amazon holds 13% share to Walmart’s ~3%, and most of Walmart’s share still runs through its stores rather than the online assortment an agent would search.
Walmart is strongest in grocery and in its physical footprint.
Amazon is strongest in selection, speed, and the digital-native fulfillment an agent optimizes for.
Found this content valuable? Share it with your network! Help others discover these insights by sharing the newsletter. Your support makes all the difference!
Amazon Prime and Advertising:
Beyond protecting the core business, the network feeds two of Amazon’s highest-quality revenue streams: Prime and Advertising.
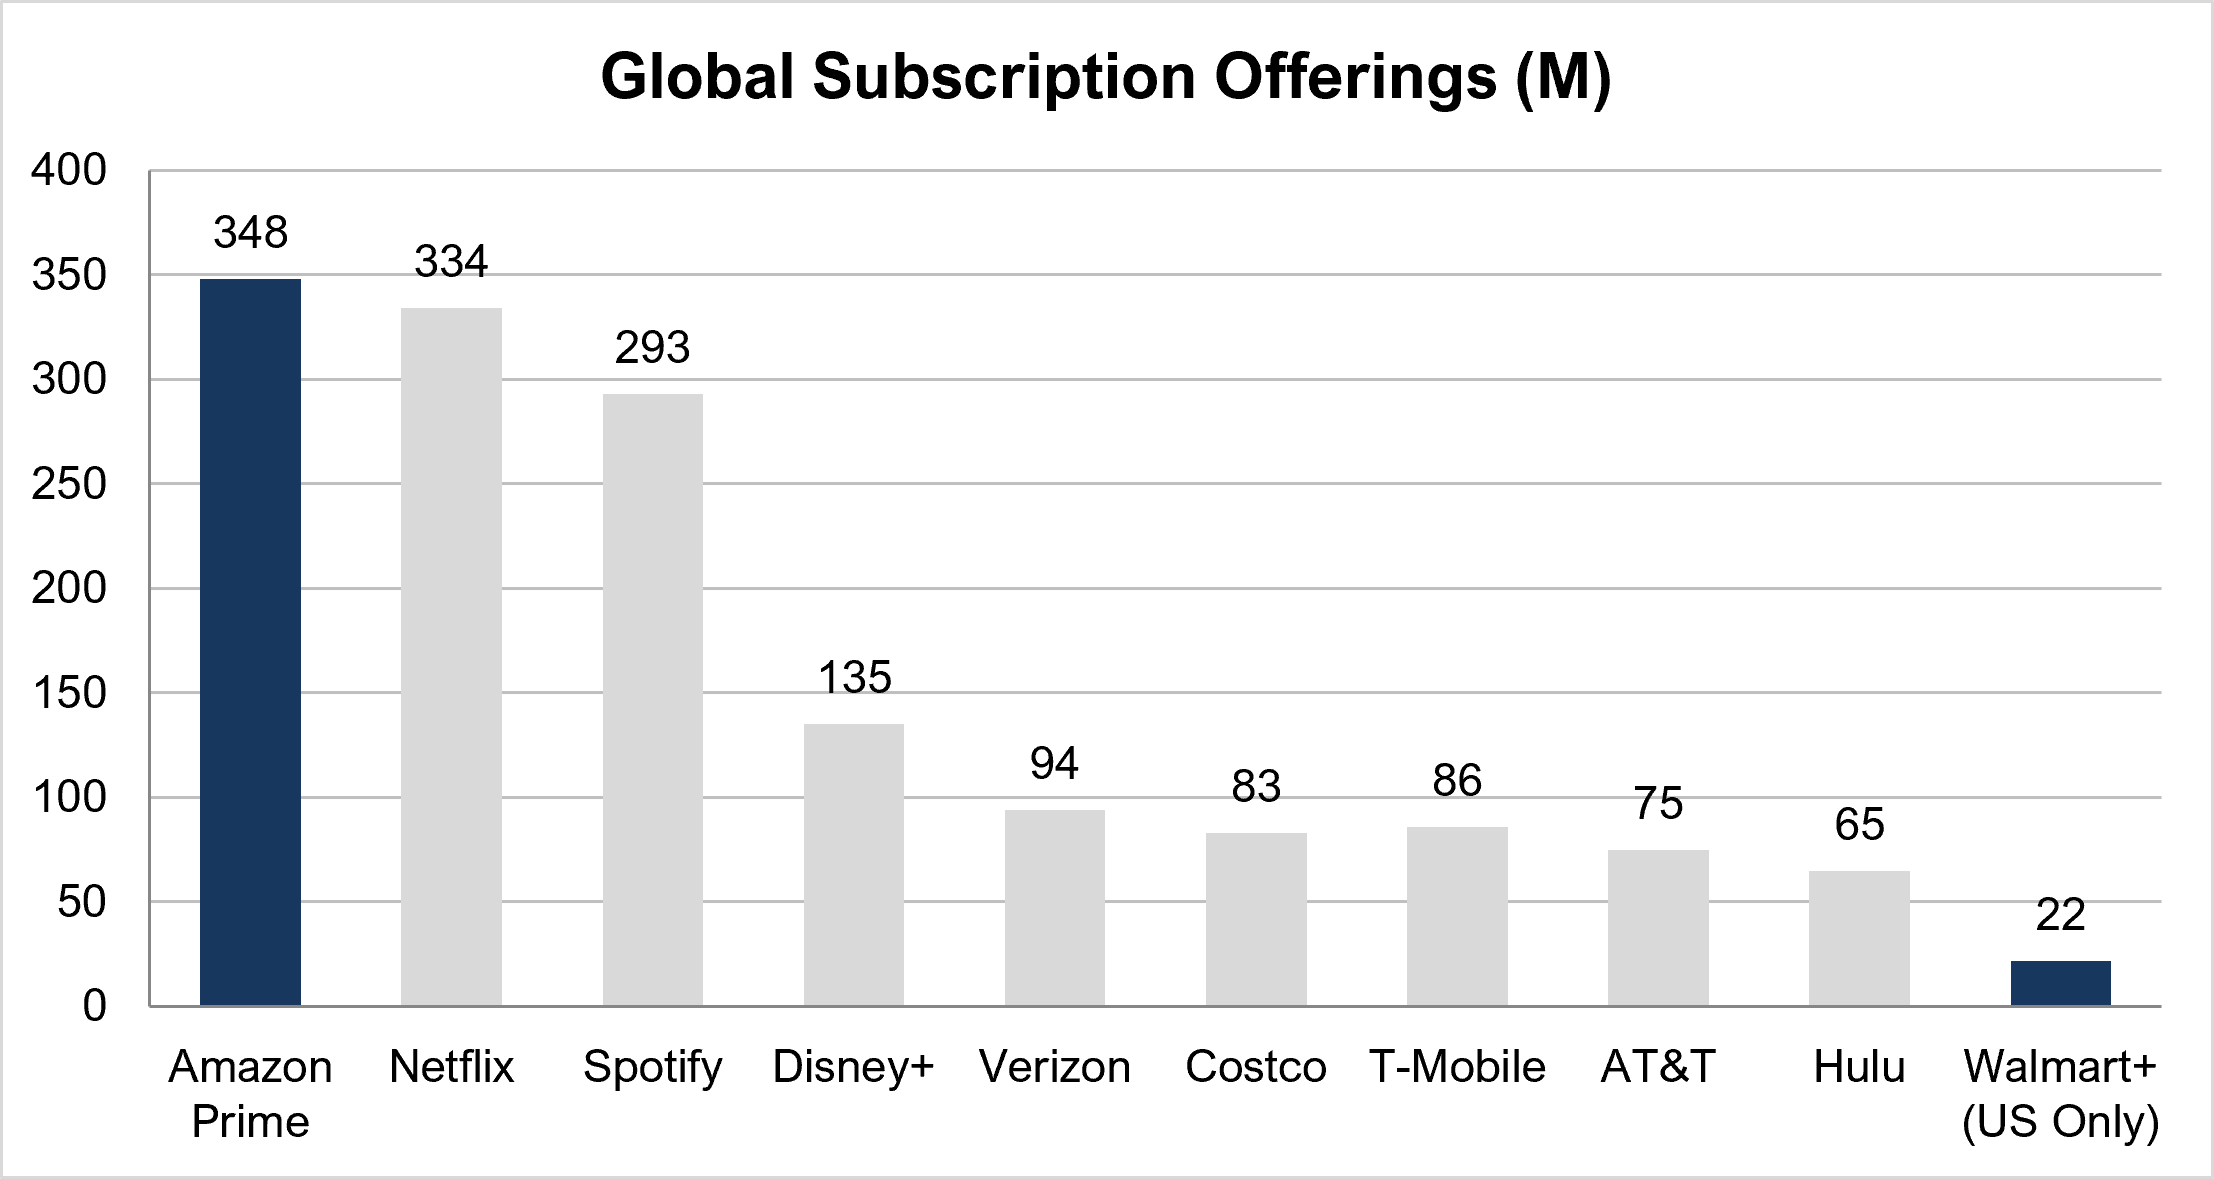
Prime is the flywheel: if you add up its parts, the bundle is worth an estimated $1,440/year, about 10x the $139/year US price.
Delivery does most of the work, with US members saving an estimated $550 in average fees in 2025, but the bundle also spans video, music, grocery, reading, gaming, and photo storage.
That gap in value is what allows Amazon to keep raising prices, as it has done over the past decade, with the price increasing about +5-8%/year since 2016.
A $20 increase would add around $3B in ARR with little expected churn, in line with past price increases.
And that doesn’t even include international expansion, which widens the runway even further. Today, Prime is available in 27 markets, with still-low penetration of roughly 33%.
It’s the membership benefit an AI agent treats as another comparable signal, the loyalty variable that helps Amazon clear the bar the machine scores against. The flywheel that drives frequency, retention, and first-party data is the same one that lifts Amazon when an agent decides what to recommend.
Advertising is more or less the same thing, only with even higher margins.
It is one of Amazon’s fastest-growing businesses, an estimated $83B in 2026 at approximately 9.0% of global ad spend, which already makes it the 3rd-largest advertising player in the world and still gaining share.
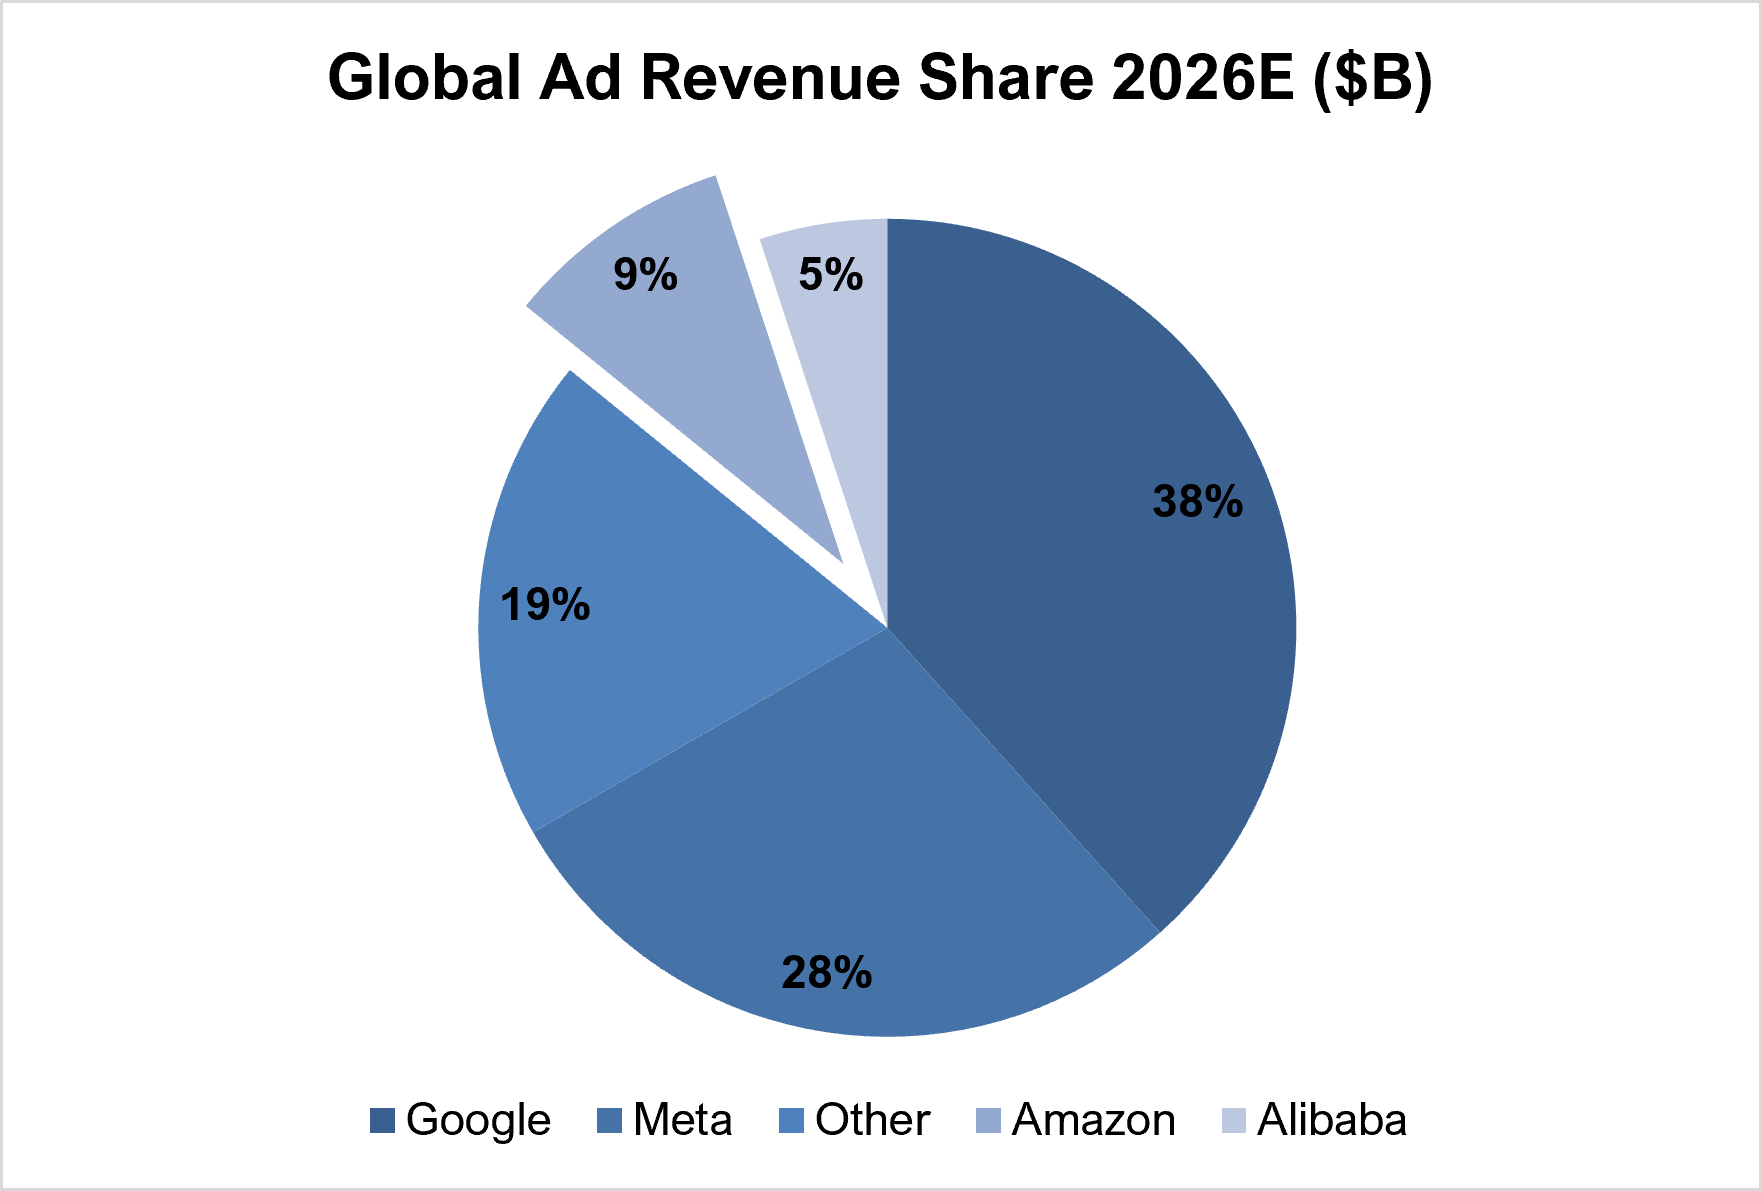
At an illustrative operating margin near 46%, advertising throws off around 36% of total operating income on a fraction of the revenue.
Agentic commerce also expands this moat even further. AI-enabled campaigns already make up more than 30% of search spend at the leading players and tend to deliver better returns, while new placements like sponsored results inside Alexa for Shopping create ad inventory rather than erase it.
Traffic, first-party data, and the delivery network to close the loop are the combination that monetizes at this margin. Amazon has all three.
Main Risks:
For all its strengths, the thesis rests on one load-bearing assumption: that Amazon continues to own where demand starts. That is true today, but it’s also exactly what agentic commerce puts up for grabs.
That is why I wrote this short section to highlight what I see as the two main risks:
The first is that discovery gets disintermediated. If the dominant shopping agent is ChatGPT, Gemini, or Perplexity rather than Alexa for Shopping, Amazon becomes a supplier inside someone else’s interface. In that world, Alexa for Shopping only wins the journeys that already begin on Amazon.
The second is that the agent isn’t a neutral judge (far from that). Every agent has an owner, and that owner has its own economics. OpenAI and Google are already building checkout and monetization into their own chat experiences, which means the intermediary may optimize for its own take rate, not for the shopper’s pure rationality.
Final Thoughts:
After everything laid out above, it becomes increasingly clear that Amazon is likely to be, once again, one of the major beneficiaries of the next technological wave: AI.
Beyond robotics, which was not even covered here and deserves an article of its own, AI is already being applied inside Amazon to create agents that help consumers buy products within its ecosystem.
Delivery speed, price, selection, and the Prime flywheel were already powerful value drivers for human shoppers. Now they may become even more important as agents begin to compare options more rationally and with less brand attachment.
The company has the catalog, the data, the fulfillment network, the delivery speed, the membership base, and the advertising engine. Each piece reinforces the others, and together they create a moat that becomes harder to attack as commerce becomes more automated.
At the same time, Amazon is currently trading at around 28x P/E - a major multiple compression versus its own history, but one that reflects the company’s slower growth profile today.
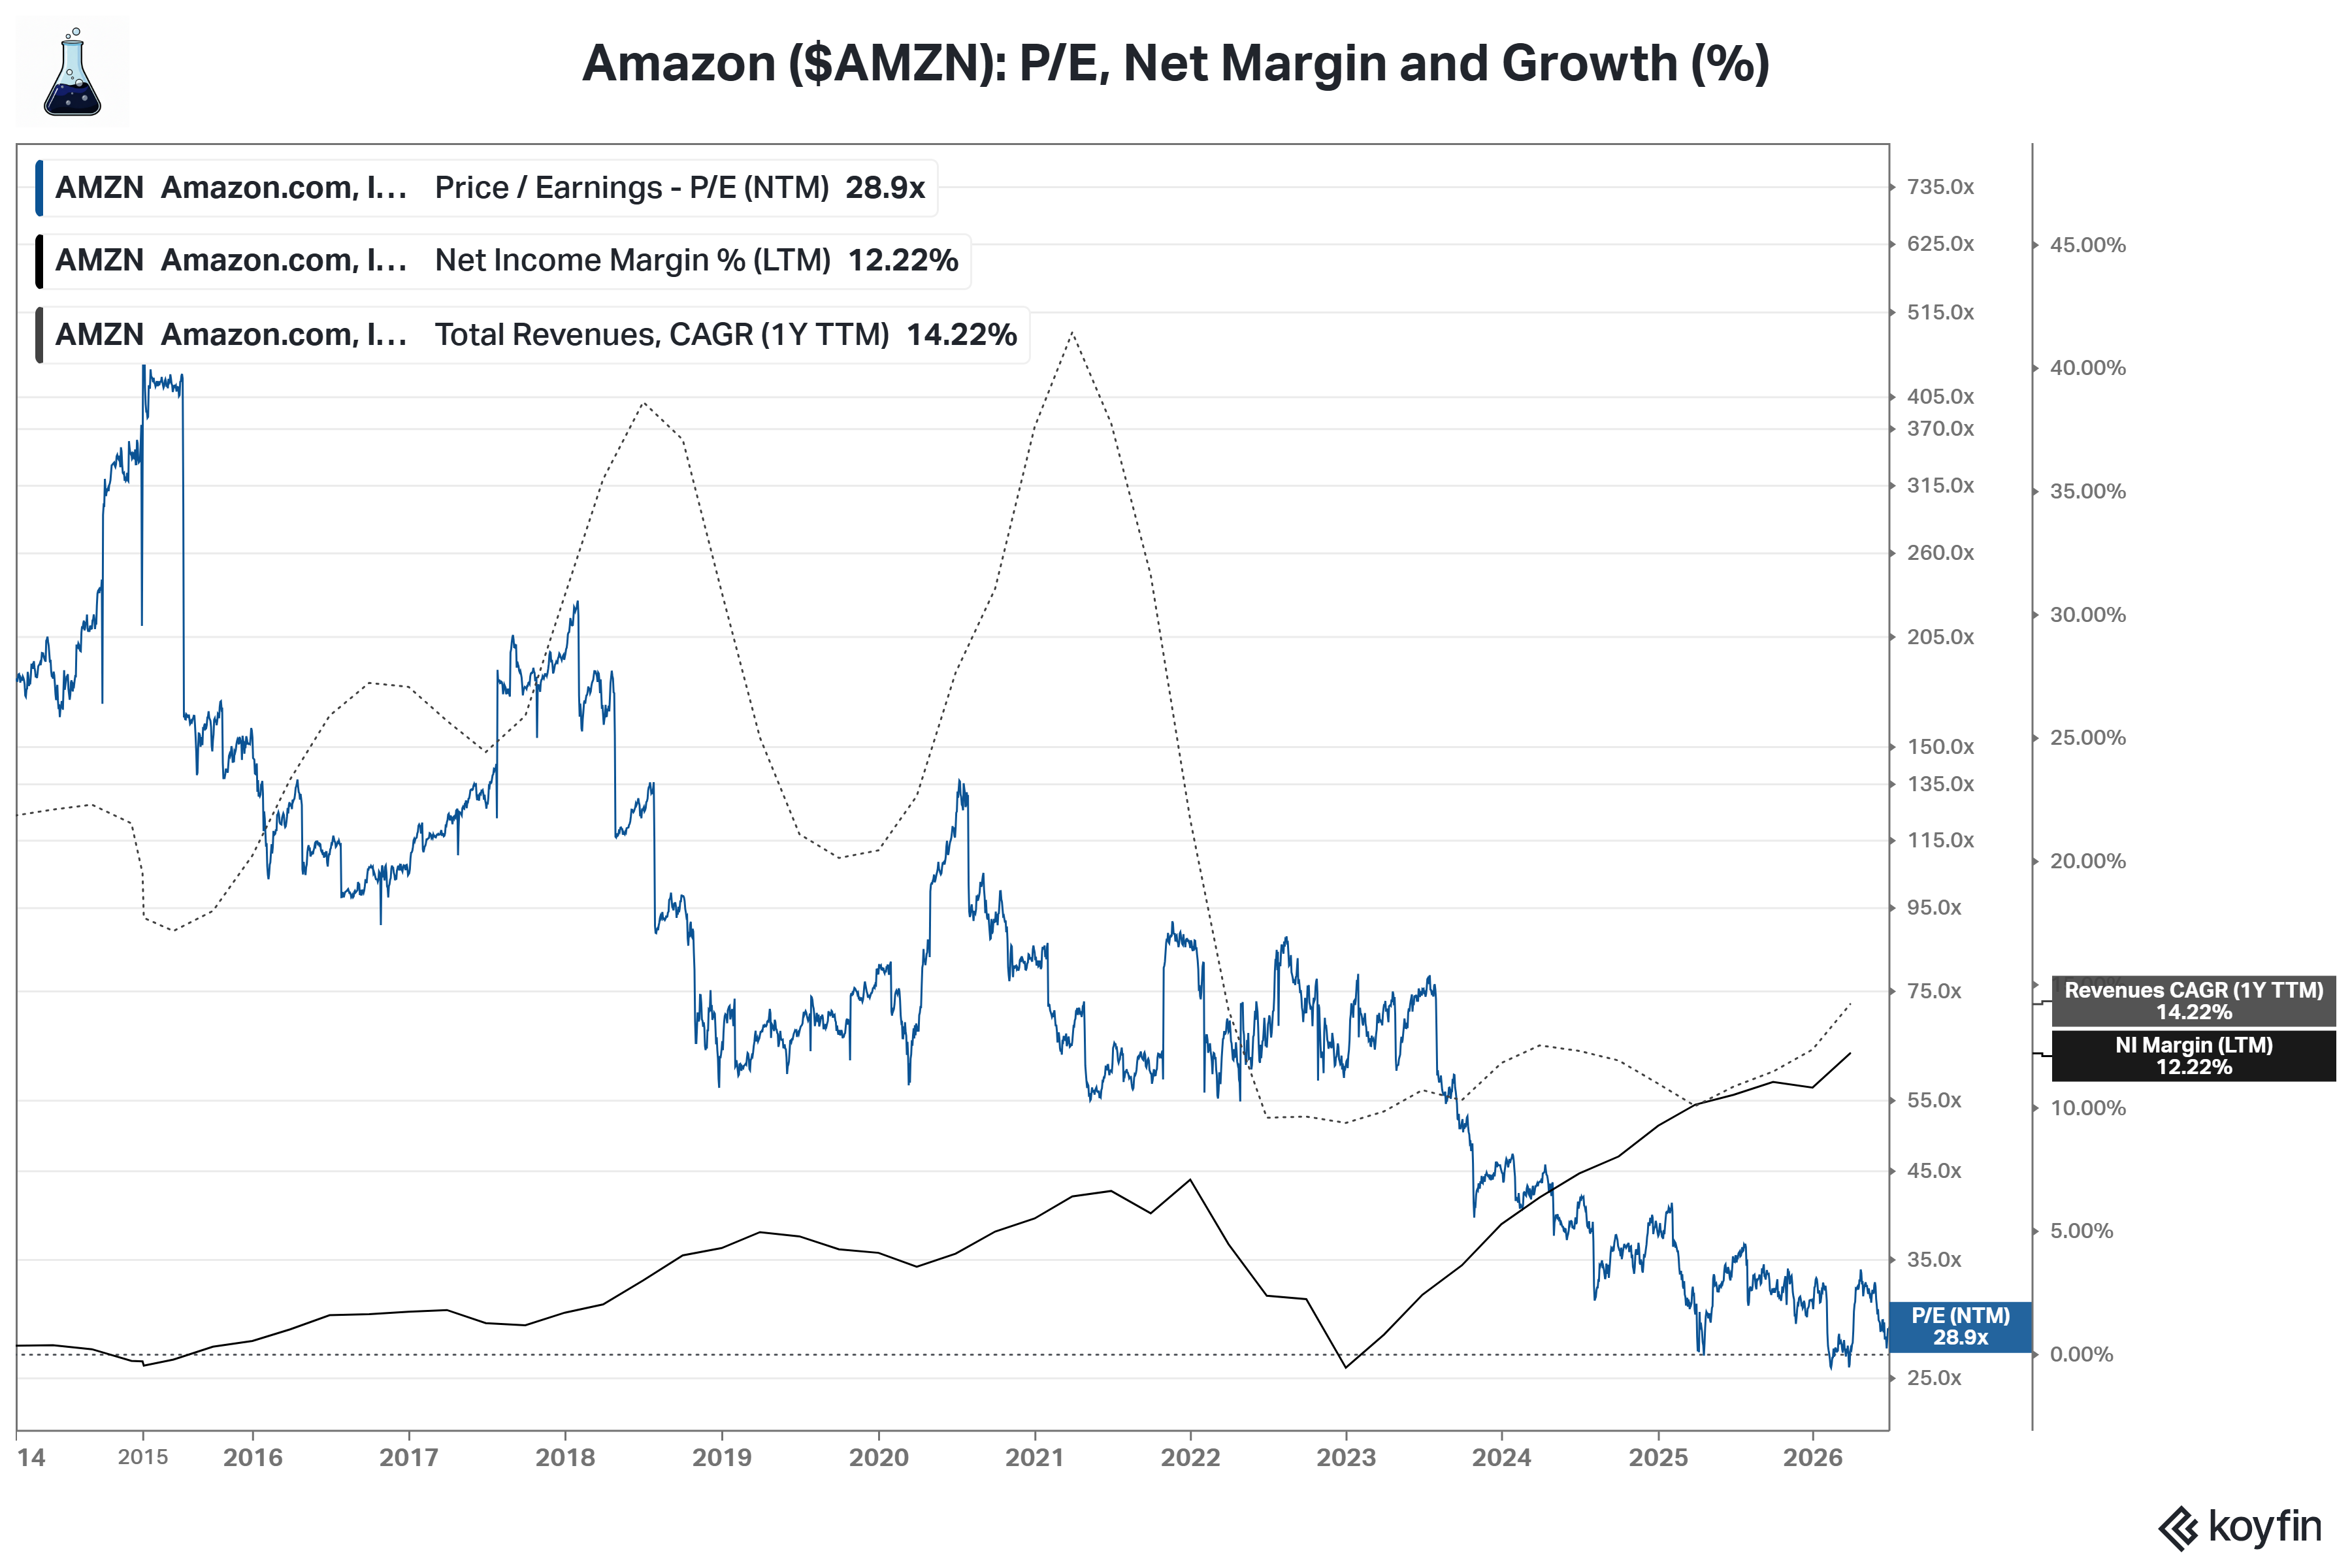
The real dilemma is whether the market is paying too much attention to the short term while underestimating the medium- to long-term runway - a runway that may only become visible 2-3 years from now.
Because if agentic commerce becomes even a fraction of what people expect, Amazon won’t be watching from the sidelines. It already owns much of the infrastructure this new shopping layer will need in order to work.
And in commerce, as in many other markets, owning the infrastructure is often a better position than merely owning the interface.
If you enjoyed this piece and want to keep investing in higher-quality businesses with a long-term mindset, consider upgrading to Jimmy’s Journal Pro.
Pro members get full access to deeper company research, portfolio updates, trade alerts, valuation frameworks, and the tools we use to think through opportunities like this one.
The goal is simple: to help you find better businesses, understand them more deeply, and build long-term wealth.
All of this for just $297/year - or $24/month.
Prices are going up soon. Join now.
Thank you for reading all the way through.
Cheers,
Jimmy
Disclaimer
As a reader of Jimmy’s Journal, you agree with our disclaimer. You can read the full disclaimer here.
Walmart wins at the very low margin grocery business and will simply try to replicate amazon’s innovations, but is inferior by just about every metric including PE. Of course, Amazon is building robots to replace its workforce while Walmart adds a new Save Card on File to its checkout that cnbc describes as their “move into tech”
Wu et al. (2026) tested 23 models on a booking task that only gently suggested favouring a sponsor, and 18 recommended the pricier sponsored option more than half the time, the most biased above 80%.
With Amazon infamously pushing its own product lines and and their growing ad business , I wonder how they'll attempt some sort of neutrality in Rufus. (or if customers even expect it in the first place)
Wu, A. J., Liu, R., Li, S. S., Tsvetkov, Y., & Griffiths, T. L. (2026). Ads in AI chatbots? An analysis of how large language models navigate conflicts of interest. arXiv.